

Irrational Analysis is heavily invested in the semiconductor industry.
Positions will change over time and are regularly updated.
Opinions are authors own and do not represent past, present, and/or future employers.
All content published on this newsletter is based on public information and independent research conducted since 2011.
This newsletter is not financial advice and readers should always do their own research before investing in any security.
Feel free to contact me via email at: irrational_analysis@proton.me
Hello and welcome to an exciting first edition of Cerebras CBRS 0.00%↑ earnings call coverage.
Two months ago, I wrote a detailed report for the IPO. Typeset in LaTeX for the special occasion.
Cerebras $CBRS Equity Research Report -- 2026 Edition

Irrational Analysis is heavily invested in the semiconductor industry.
Afterwards, one of my hedge fund friends called me, confused. He could not tell if I was bullish or bearish.
I believe the following statements to be true and do not view them as contradictory.
I have been a fan of Cerebras since 2019.
Cerebras should have died due to incompetence years ago.
Cerebras ultra-fast inference is an incredible niche with enormous untapped potential.
The WSE has several fundamental flaws and management is in partial denial and may be appropriately compared to clowns.
Most of the time, activist investors get involved for lame reasons. Force management to cut costs, more buybacks, “strategic review” (sell yourself for scraps).
Today marks the glorious beginning of the dumbest, most entertaining activist campaign in history.
I am a proud shareholder of CBRS 0.00%↑.
You could say I am a holder of share.
We shall have such fun along the way.
Contents:
Updates on Wrong Parts of IPO Report
Earnings Call Transcript
Guide for Financial Analysts
[1] Updates on Wrong Parts of IPO Report
After publishing, several people pinged me on several wrong assumptions, particularly in the modeling sections.
Biggest info was that ASP of a WSE-3 rack is closer to $700-850K. A few other tweaks were needed. See the bold comments on what I changed and why.
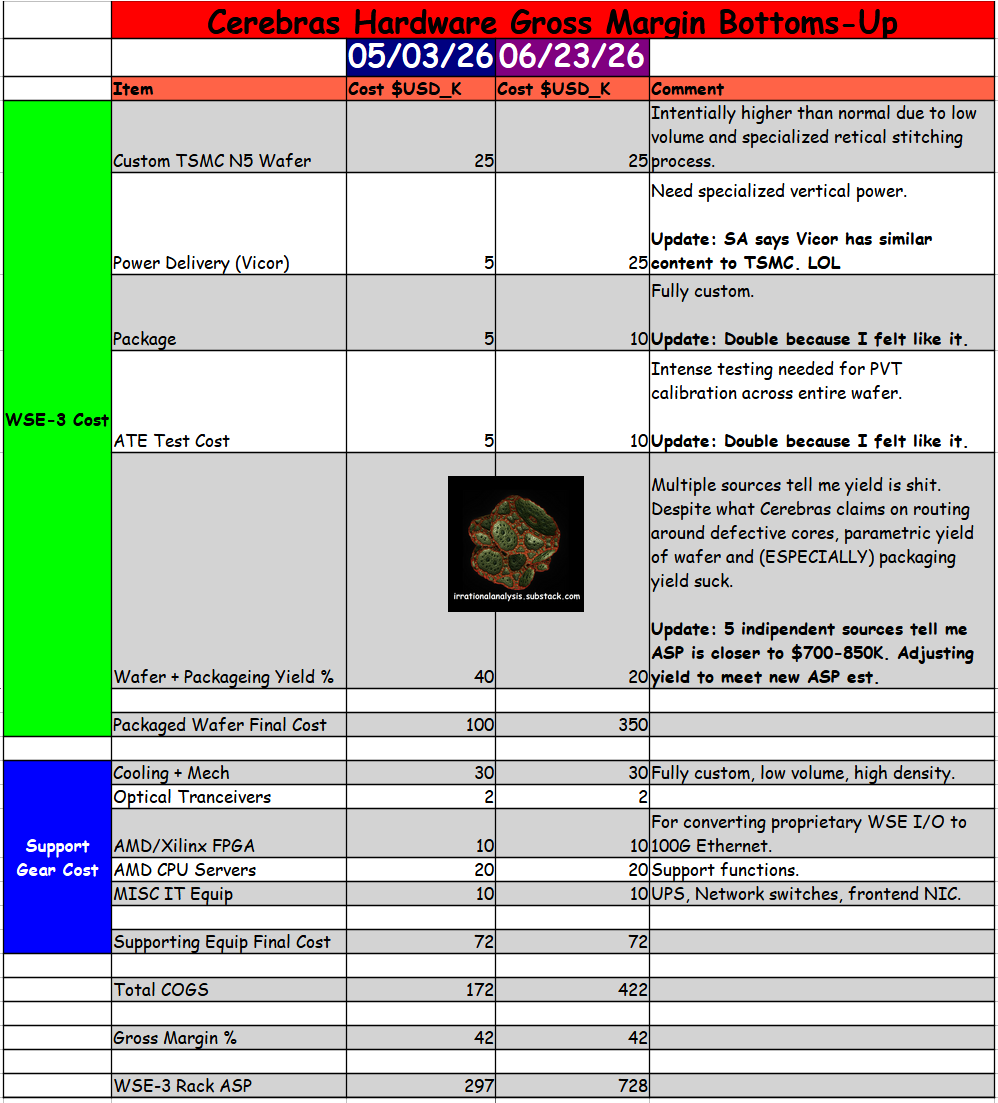
There is a lot of (pointless) debate on wafer yield vs packaging yield.
I believe the wafer yield is quite high, easily above 90%. When Cerebras management claims near-100% wafer yield because of routing around defects, sure that is not a crazy claim.
But the only way to explain ASP and gross margins is assuming total yield is horrific. I think they get killed on packaging yield.
Maybe 100% of wafers from TSMC are good but 4/5 wafers fucking die in the packaging process? How the fuck do you explain these atrocious numbers?
Second major issue was my assumption on Tok/s/user.
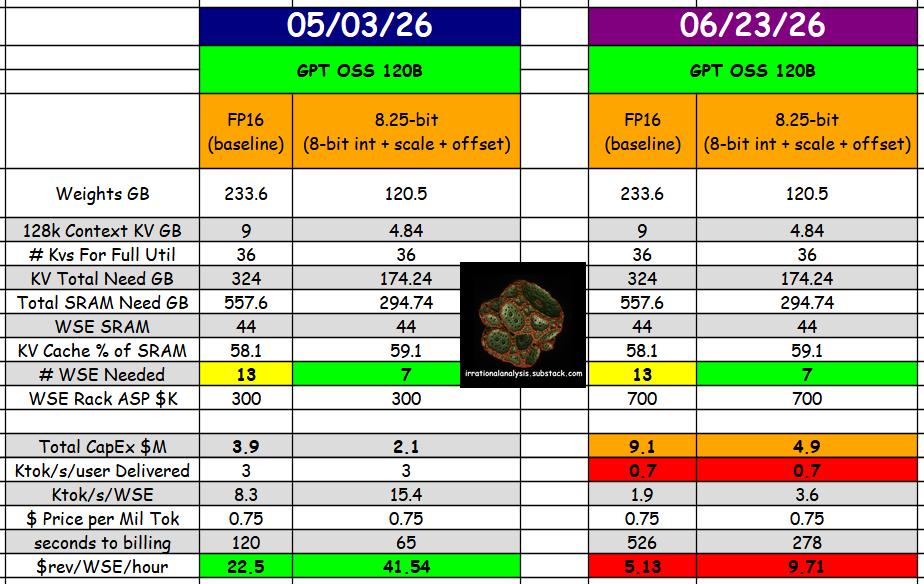
Apparently the openrouter 3K number is bullshit. Updated to 0.7K.
Also updated ASP from $300K to $700K.
Finally, I managed to get a third uncorrelated source on the Cerebras/Groq/Nvidia palace intrigue.
Invertedly.
The person who gave me this nugget info has no idea on the correct extrapolation.
Information asymmetry is a funny thing.
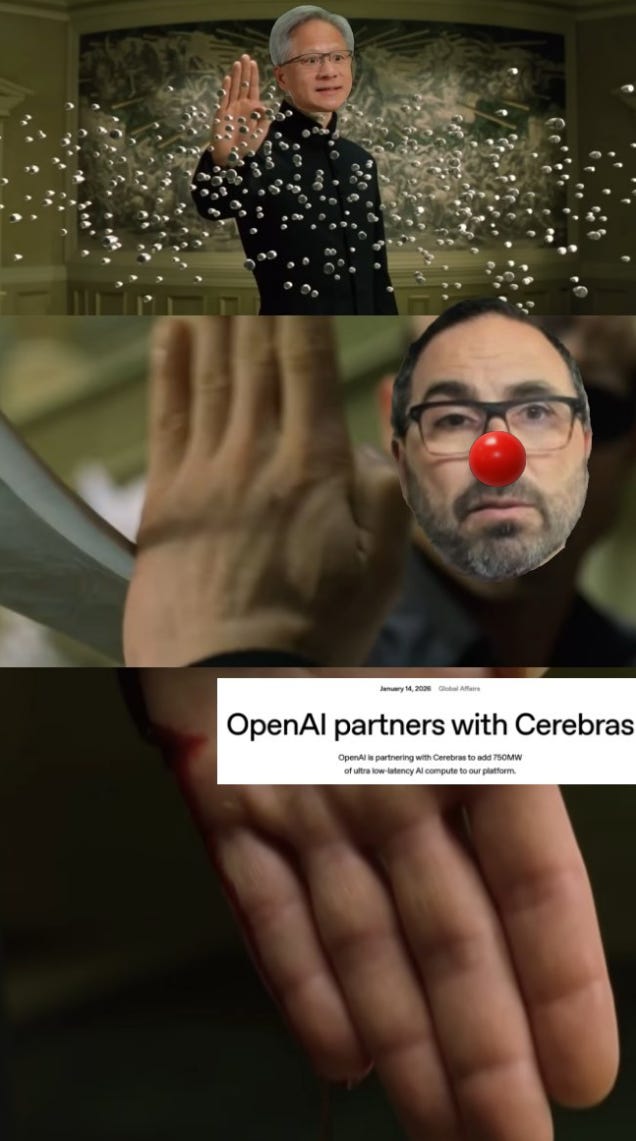
Debating if I want to make this call without a 4th uncorrelated source.
For now, let’s just say what happened with Groq is (90% confident) very linked to Cerebras. Highly correlated events.
[2] Earnings Call Transcript
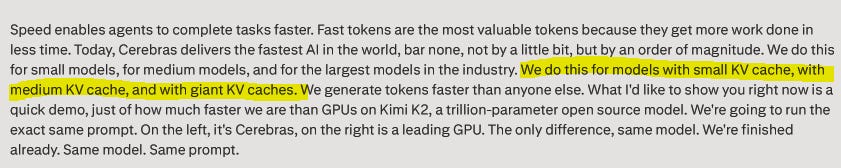
At what economics??? Everyone with a basic understanding of this space knows KV cache kills your economics.
People are offloading KV cache to fucking NAND boxes and you clowns are storing it on SRAM.
KV cache competes with model weights for the same scarce resource.
YOU NEED TO OFFLOAD KV BUT I/O ISSUES BLOCK STREAMING AS A VIABLE OPTIONS. ADMIT THE PROBLEM AND GO FIX IT. YOU RAISED MONEY FROM IPO GO SPEND IT TO FIX DISASTER BOTTLENECK.
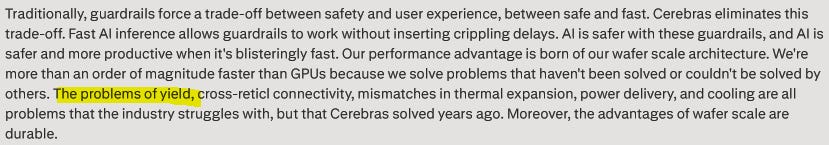
Bro you seriously bragging about yield? Your yield has to be complete dogshit even after all these years. No other way to explain the financial numbers. Why don’t you share the numbers? I am at 100% wafer level yield, 20% packaging yield.
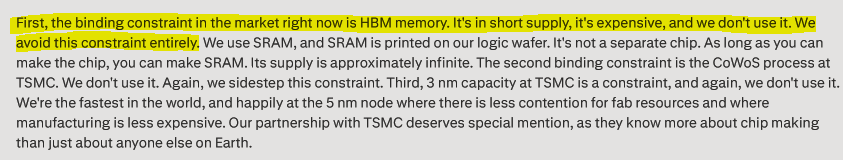
Feldman makes very good points here that I completely agree with.
Imagine if they had enough I/O to offload KV to NAND boxes. Think of how much bigger models and how much better the economics would be if KV did not compete with model weights in SRAM.
This is what is so frustrating. Cerebras really has something and could be so much better. They just need to fix a few (rather serious, but largely solvable) problems.
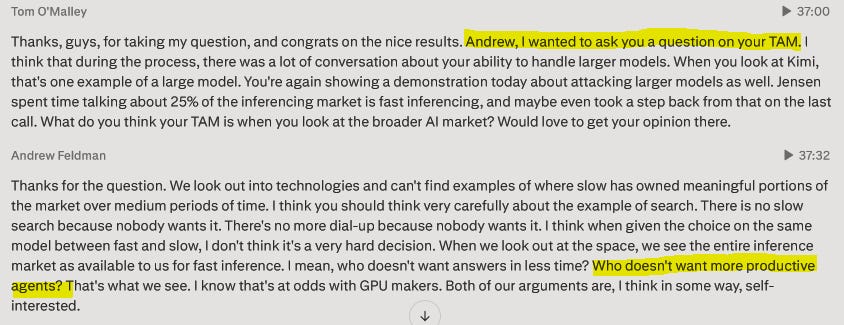
I agree TAM is infinity. Too bad it takes a comical number of WSE to hold a model because KV CACHE COMPETES WITH MODEL WEIGHTS IN SRAM and WSE-3 DOES NOT SUPPORT FP8 OR LOWER.
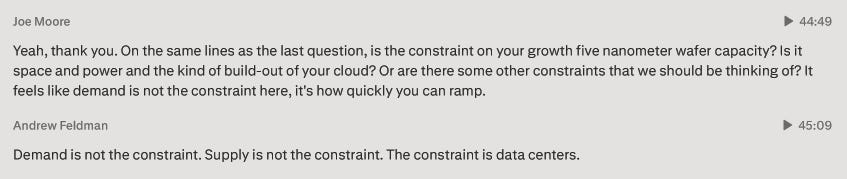
The constraint is your horrific packaging yield.
Ok let’s play a game.
Here is the full Excel model for both COGS/GM and inference tokenomics.

I would like every sell-side and buy-side analyst to download the above model, make your own changes, and decide for yourself who has a “misunderstanding”.
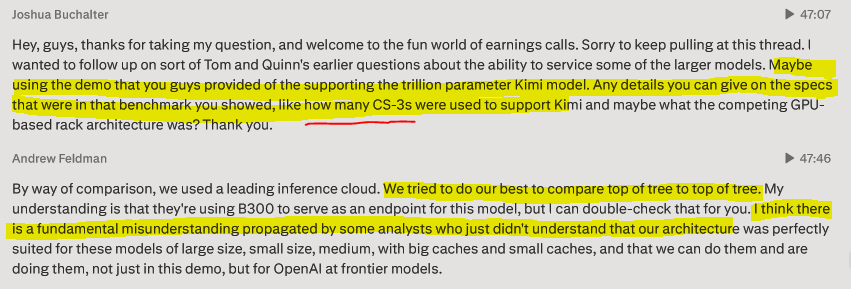
Joshua Buchalter of TD Cowen asked a direct question and Andrew Feldman refused to answer.
“How many CS-3" were used to support kimi and maybe what the competing GPU=based rack architecture was.” — Josha Buchalter, TD Cowen
[3] Guide for Financial Analysts
There are only three factors that matter.
[1] WSE-4 Floating-Point Format Support
WSE-3 is from 2024.
WSE-4 should be fairly far-along in the design process. Ideally it needs to support FP4 but if it’s only FP8 maybe that is forgivable. Willing to hear arguments from them that FP8 is appropriate for the architecture.
I refuse to believe they are stupid enough to stay on FP-16. Someone please confirm this.
[2] WSE on/off Wafer I/O
This is the blocker for KV cache offload/streaming. Two un-correlated sources told me Cerebras is working on “face-to-face” I/O. Unfortunately I don’t have more details as both the sources are not technical.
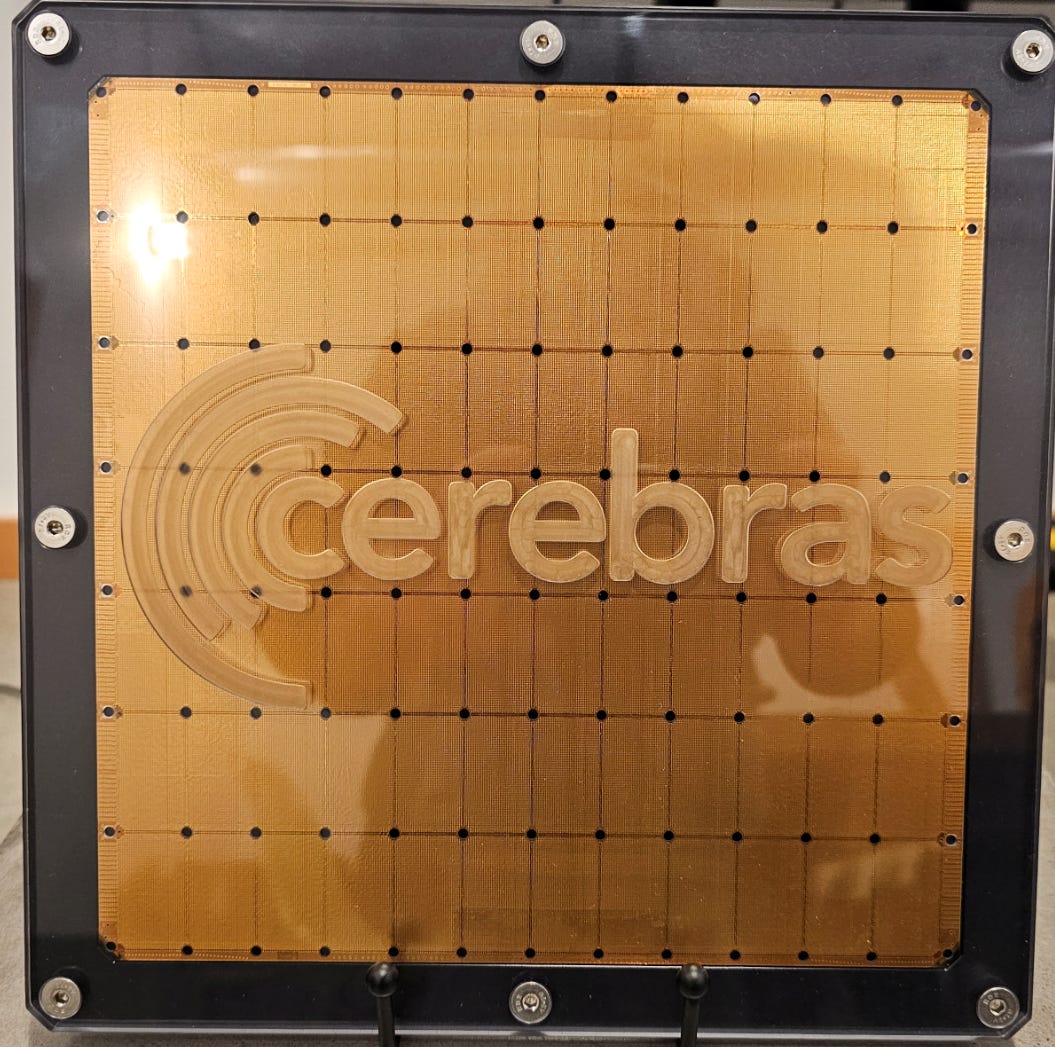
My best guess is for some reason the I/O is limited to being a NoC extension alongside one axis. NoC probably runs at something slow-ish like 1 GHz.
Right now, only two edges are useful for I/O. Or might be only one edge IDK the numbers are so bad lol.
“Face to face” I/O likely means using the copies trapped between rows of reticles. Electrically, this makes sense. Physically (cooling, alignment, packaging) this is a nightmare.
Very curious on their progress and the underlying details.
[3] Horrific Gross-Margins —> Horrific Packaging Yield
They should honestly have an investor day and dedicate half of it to the yield improvement roadmap.
Again, I am modeling 100% wafer yield, 20% packaging yield to get 42% hardware GM.
If you bump the packaging yield up from 20% to 50% gross margins go from 42% to Nvidia-level 72%.
So much potential!
I am still confused. Are you bullish or bearish or just don’t know what?
I don’t have a clue what you said or mean. Perhaps a few education episodes explaining what you’re talking about.